
In his book Skin in the Game, Nassim Nicholas Taleb distils several financial and philosophical principles into a single, disarming sentence:
“Don’t tell me what you think; tell me what you have in your portfolio.”
That remark has strongly influenced how I think, not only about investing but also about accountability, coherence, and decision-making under uncertainty.
It has also inspired me to write not just about my investment portfolio, but about my broader personal asset allocation as it has evolved over time.
By personal assets, I mean anything I own. This includes both investment and non-investment assets.
I deliberately track assets outside my purely investment portfolio because it provides a more complete picture of my financial outlook, risk profile, and long-term wealth trajectory.
2026 ASSET CLASSES
When assessing investments, we face multiple asset classes, each defined by its liquidity, ownership structure, time horizon, and risk–return profile.
In my broader research on Global Wealth Across Assets, I’ve examined these categories at a macro level. At a personal level, excluding collectables and art, I now have exposure to most major asset classes.
Reviewing my portfolio in 2026, I realise I’ve made several structural adjustments compared to my 2023 asset allocation.
Specifically, I have:
Introduced Private Equity and gold
Reduced exposure to P2P lending and direct physical real estate
Increased allocation to REITs and cash equivalents
What follows is a detailed breakdown of my portfolio’s asset classes and what I like about each.
EQUITY
Equity remains the largest component of my allocation. This is a deliberate, fairly assertive stance, typical of an accumulation phase, aimed at achieving my Financial Freedom number.
At the same time, I like to think I am also playing some defence through diversification, in preparation for an eventual wealth-preservation phase.
My equity exposure is primarily held through broad ETFs tracking the S&P 500 (SP5C), MSCI World (VWCE), and European equity markets (VERX). These instruments provide me with diversified, low-cost exposure to global growth.
Alongside this core, I also hold a small allocation to listed investment holdings, notably Exor and Investor AB (my review). While technically traded as single stocks, they are better understood as long-term ownership vehicles that control diversified portfolios of operating businesses, both listed and unlisted (as per the images below).
What attracts me to these companies is not short-term performance, but their owner-operator mindset. Both Exor and Investor AB think in decades, not quarters. Capital allocation, governance, succession, and balance sheet resilience are treated as strategic assets rather than afterthoughts.
EXOR Holding

Investor AB Holding
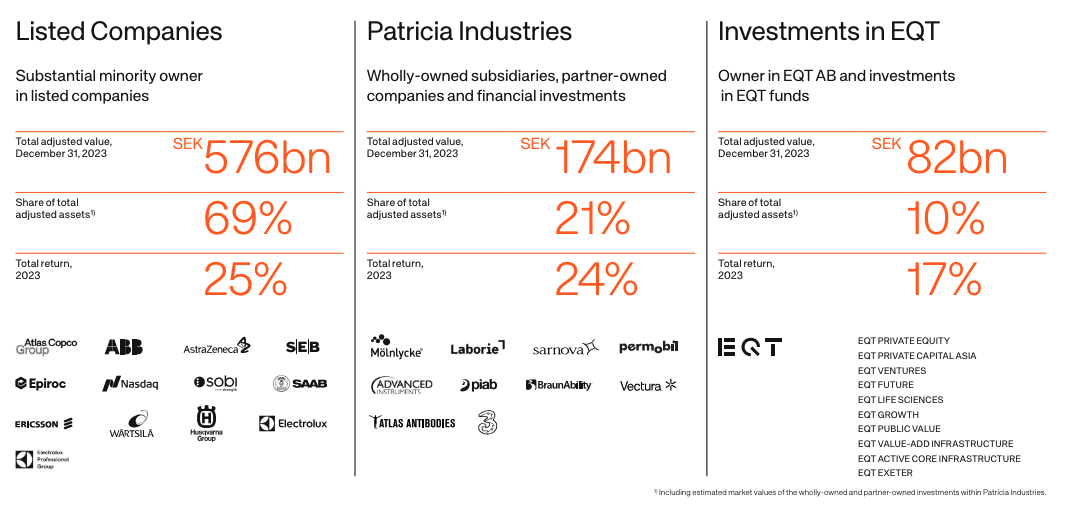
As a shareholder, I value their disciplined approach to deploying capital, their willingness to hold through cycles, and their transparency in communicating decisions.
I genuinely enjoy reading their annual reports and tuning into quarterly or annual shareholder updates — not because I expect constant action, but because they offer a rare window into how thoughtful capital stewards reason over time.
I’ll admit it openly: holding only ETFs can feel a bit dry. A few carefully chosen holdings like these make investing more engaging and intellectually alive. They encourage me to follow specific industries, reflect on business models, and observe how real-world decisions compound over long periods — which, ultimately, is the whole point of investing.
CASH (EQUIVALENT)
At first glance, the relatively high cash allocation shown in the chart can be misleading.
A large portion consists of short-term Treasury instruments (C3M), which are technically classified as cash equivalents rather than bonds. This bucket includes emergency reserves, short-term liquidity needs, and a tactical “war chest” designed to be deployed during significant market dislocations.
So rest assured: I remain committed to sweating my assets and protecting purchasing power against the silent wealth destroyer known as inflation. While cash is structurally defensive, part of this allocation is deliberately tactical and can be redeployed into risk assets if compelling opportunities arise—such as during a sharp market correction.
BONDS
Fixed income plays a stabilising role in my asset allocation, primarily as a risk-diversification tool. My exposure includes both U.S.-based (ILTB) and corporate EU-bonds (VECA).
This is an asset class I expect to keep relatively stable over time. Its main function is to reduce overall portfolio volatility and help smooth returns across market cycles.
REAL ESTATE

Last year, I fully exited my direct ownership of physical real estate properties. While I appreciated both the sense of ownership of a family home and the experience of being a landlord while renting it out, I eventually grew tired of the business model and the operational effort required to manage it properly.
My perspective on this is better articulated in a separate article of mine, “Is Your home an investment?”
No judgment here. We are all at different stages of life, with different priorities. At this point, I prefer to access real estate through REITs (TRET).
REITs are a vehicle I’ve used for many years. They offer attractive risk-adjusted returns with minimal effort, high liquidity, and broad diversification across regions and property types. For me, that combination is both strategic and convenient.
Still, in a typical spirit of the exception that confirms the rule, I have recently bought shares in a real estate property that includes beachfront land in northern Bali. This is a modest investment, structured either for a three-year exit or for a longer horizon if development plans move forward. I consider it a pet project rather than a core holding.
COMMODITIES (GOLD)

Gold is a relatively recent addition to my portfolio. I bought it back in July 2024 after an extensive discussion with a wholesaler, with whom I tested all my questions about the overall gold market.
My exposure is entirely through financial instruments (SGLD); I do not hold physical gold. Between transaction costs, storage, security, and liquidity concerns, physical ownership does not suit me.
Over the past two years, gold has experienced significant growth, and in hindsight, it has clearly been helpful amid market volatility.
That said, it remains one of the most intellectually challenging asset classes to assess.
Aswath Damodaran has repeatedly argued that gold cannot be valued in any conventional financial sense. Likewise, John Bogle famously claimed that gold is not an investment at all.
Still, within modern portfolio theory, a modest allocation to gold can make sense as a diversifier. I plan to explore this asset class in more depth in a dedicated article.
P2P and Crowdfunding

I have studied, tested, and invested in peer-to-peer lending and crowdfunding platforms for nearly a decade. Overall, it is not an area I find particularly compelling.
With few exceptions (Mintos), the P2P sector remains largely unregulated, and defaults at both the borrower and platform levels are common. Jean Galea, a fellow blogger, updated the list of weak P2P lending platforms and those that have gone bust.
For impact-driven reasons, however, I continue to invest selectively in crowdfunding solar energy projects through Trine. I still consider it a thoughtful way to deploy capital: to expand access to electricity, support small businesses, and contribute to the SDGs by reducing CO₂ emissions.
PV / PE (Private Ventures / Private Equity)

Private Equity represents a relatively recent step for me into a new asset class.
I have directly acquired shares in an Indian startup—Ametra—driven by an interest in the Indian market—too large and dynamic to ignore—the fintech sector, and the broader ecosystem supporting entrepreneurship and innovation.
Until now, my exposure to this space had mostly come through donor-funded projects, so engaging privately felt like a natural, though still experimental, extension of that experience.
Private equity investments are inherently illiquid and follow a very different economic logic compared to public markets.
I treat this exposure as a long-term, high-conviction pet project. There is a lot to learn, a lot to monitor (trends, markets, currency risk, regulations), and a lot I can simply wait and see.
Still, I love engaging with the brilliant team on quarterly calls. Assuming things evolve positively, any realistic exit would likely occur over a 7–10-year horizon.
Crypto
Regarding cryptocurrencies, I haven’t written much over the years. I have, however, shared videos featuring Aswath Damodaran (who provocatively frames crypto as “millennial gold”) and Nassim Nicholas Taleb (who goes much further, calling Bitcoin a Ponzi scheme). That contrast alone says a lot.
Crypto is, by nature, a hot and deeply polarising topic, often surrounded by a quasi-cult, techno-ideological aura. Out of curiosity, I do own a small amount of Bitcoin, but I wouldn’t say I’m particularly into it.
At best, I view cryptocurrencies as a highly speculative asset class. I can genuinely respect the underlying technology and the intellectual elegance of blockchain systems, but I struggle to see Bitcoin as money.
As a medium of exchange, it is inefficient: transaction costs can be high, throughput is limited, and it works poorly for everyday payments (unless one is operating at the margins of the system).
As a unit of account, it fails outright: price volatility makes it unusable as a stable measure of value.
As a store of value, it remains speculative: again, volatility dominates any narrative of stability.
Another interesting — though not entirely neutral — voice is Elon Musk, who has criticised Bitcoin on two engineering grounds rather than ideological ones.
First, Bitcoin mining is environmentally inefficient. In Musk’s view, energy consumption scales faster than real economic utility. A system that burns enormous amounts of energy without a commensurate gain in productivity is unlikely to be socially or politically tolerated forever; it will eventually be regulated, redesigned, or abandoned.
Second, Bitcoin is simply bad at being money. From an engineering perspective, it is slow, processes few transactions per second, and becomes expensive to use during periods of congestion. These are not philosophical objections — they are design constraints.
What about other cryptocurrencies? Clearly, there is no shortage of alternatives. Based on fundamentals alone, I have not studied them in sufficient depth, and therefore I have not invested in any of them… at least not yet.
As Warren Buffett has often reminded us:
Do not invest in what you do not understand.
For now, that principle still guides my approach to crypto.
Possessions / Items
This asset category is deliberately small and consists of physical, non-investment items.
It reflects the reality that most personal possessions—furniture, clothing, bikes, guitars, memorabilia, technology—tend to depreciate or have a limited shelf life, and therefore do not retain market value over time.
That said, these items add value to daily life. Some are essential; others improve comfort, productivity, or personal enjoyment.
As an expat, I have moved frequently and kept a relatively small inventory of personal belongings. While I embrace a degree of minimalism and frugality, I still enjoy owning quality items.
Financially, however, these possessions do not function as assets that protect purchasing power or hedge inflation. This is also the category where overspending can quietly accumulate, sometimes leading to consumer debt for items with little lasting value.
For me, discipline here means prioritising quality, durability, and genuine personal appreciation. By being intentional about consumption, I aim to limit irrational purchases and keep costs under control
Disclaimer
This overview is presented purely as an educational case study. The allocation choices and instruments mentioned are not investment advice; they are shared to offer a framework for thinking about how different asset classes interact within a personal balance sheet.
The more I reflect on my own asset allocation and its evolution over time, the more I realise how subjective this process really is. It reflects where I am in my financial journey, my risk profile, my base currency, and my lifestyle and financial goals. Based on your own circumstances, your asset allocation will almost certainly look different, and that is perfectly fine.
Until next time, enjoy your financial journey.
If you like this article on my 2026 Asset Allocation, check out other Mindset, Personal Finance and Investment content in my Archive, YouTube videos, and Audio Podcasts.